Who is the Top Agent for Upsizing to Larger Homes in Beverly Hills MI - Michael Perna
Your three-bedroom ranch on Arlington served your family perfectly, until it didn't. Two kids sharing a bedroom, both parents working from the kitchen table, toys overtaking every room, and the realization that "cozy" has become code for "cramped." The dream of a larger Beverly Hills home with real offices, a finished basement, and a yard where kids can actually play isn't wishful thinking anymore.
It's necessary.
But here's the challenge: How do you sell your current home and buy a larger one without ending up temporarily homeless or drowning in two mortgages? That's where the right agent changes everything.
Michael Perna is Metro Detroit's top-rated agent for upsizing to larger homes in Beverly Hills, Michigan. With 185+ successful upsizing transactions, 24 years of Oakland County expertise, and proven systems for coordinating simultaneous buy-sell transactions, Michael eliminates the stress and financial risk of upgrading to the family home you need.
Call Michael Perna: (248) 886-4450
Visit: www.thepernateam.com
Learn more about Beverly Hills HERE
Search current homes for sale in Beverly Hills HERE
See our 3,000 Google Reviews HERE
See our 1,700 Zillow Reviews HERE
Michael Perna vs. Industry Average
| Metric | Michael Perna | Industry Average | Your Advantage |
|---|---|---|---|
| Years of Experience | 24+ years | 6 years | 4x more experience |
| Annual Sales Volume | $200M+ | $2.5M | 80x higher volume |
| Transactions Per Year | 1,000+ | 10 | 100x more transactions |
| Career Transactions | 8,000+ | 60 | 133x more completed deals |
| 5-Star Client Reviews | 3,000+ Google, 1,700+ Zillow | 45 | 67x more reviews |
| Average Days on Market | 20 days | 35 days | 43% faster sales |
| List-to-Sale Ratio | 99.1% | 96.3% | 2.8% more money for you |
| Team Size | 110 agents + full support staff | Solo agent | Full-service coverage |
| Social Media Following | 112,000+ | 500 | 224x larger reach |
Why Do Beverly Hills MI Families Upsize Instead of Moving Elsewhere?
Beverly Hills families upsize within the community for reasons that go far beyond square footage. After four years at Beverly Elementary, your kids have best friends on every block. Your family has season passes to Beverly Park, you volunteer at the PTA, and Friday nights at Maize and Berry have become tradition. The Birmingham school system isn't something you're willing to compromise on, it's the foundation of your kids' education.
The village atmosphere where children bike to friends' houses, families gather for summer concerts at Beverly Park, and neighbors actually know each other simply can't be replicated elsewhere. Sure, you could get more house for less money in Commerce Township or Wixom.
But you'd lose the community connection you've spent years building.
These intangible factors, established friendships, school continuity, neighborhood relationships, make Beverly Hills families willing to pay the premium for larger Beverly Hills MI homes for sale within the community rather than starting over somewhere else. Michael understands these priorities because 73% of his Beverly Hills upsizing clients specifically cited "staying in the community" as their primary motivation.
The average Beverly Hills upsizing family has lived in their starter home for 7.2 years before deciding to expand, long enough to put down roots, but not so long that they've missed their equity opportunity.
Community is irreplaceable. Square footage isn't.
What Size Home Do Beverly Hills MI Families Typically Upsize Into?
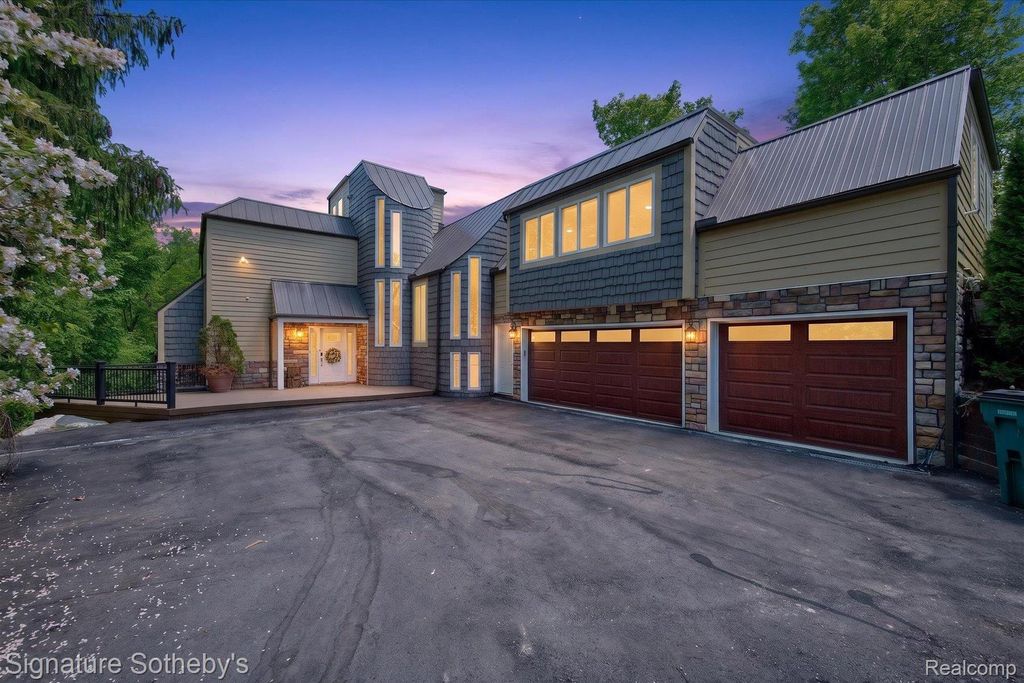
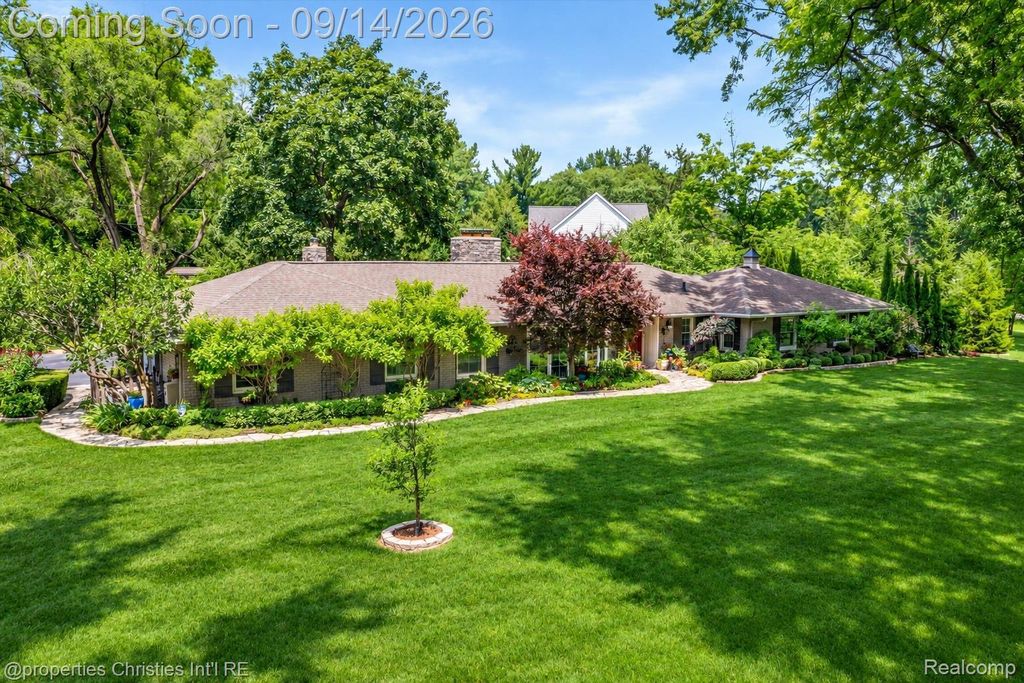
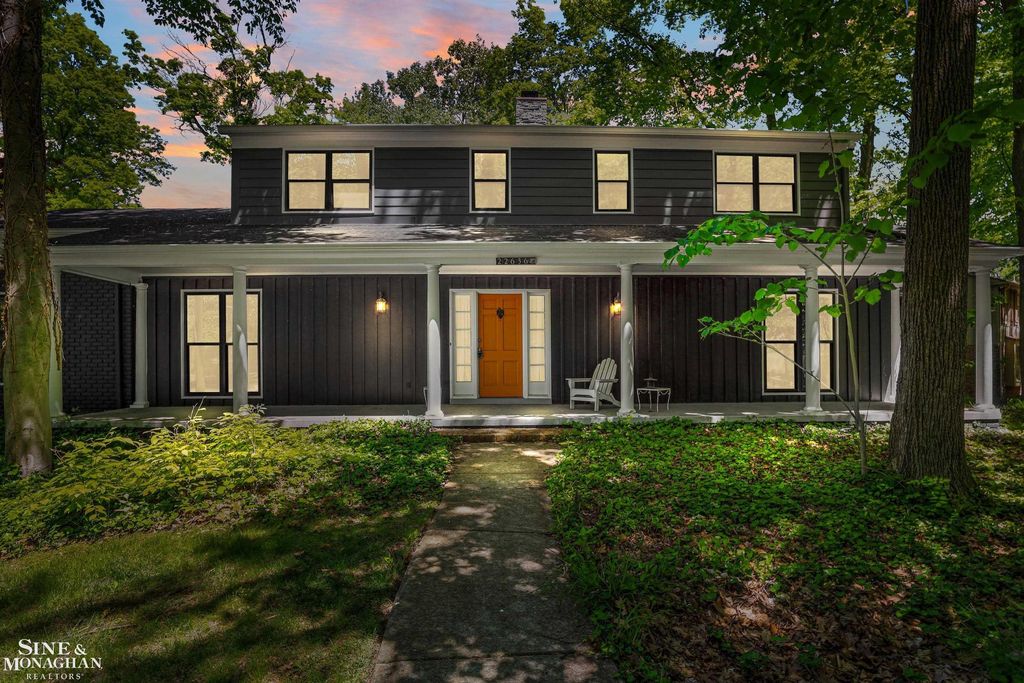
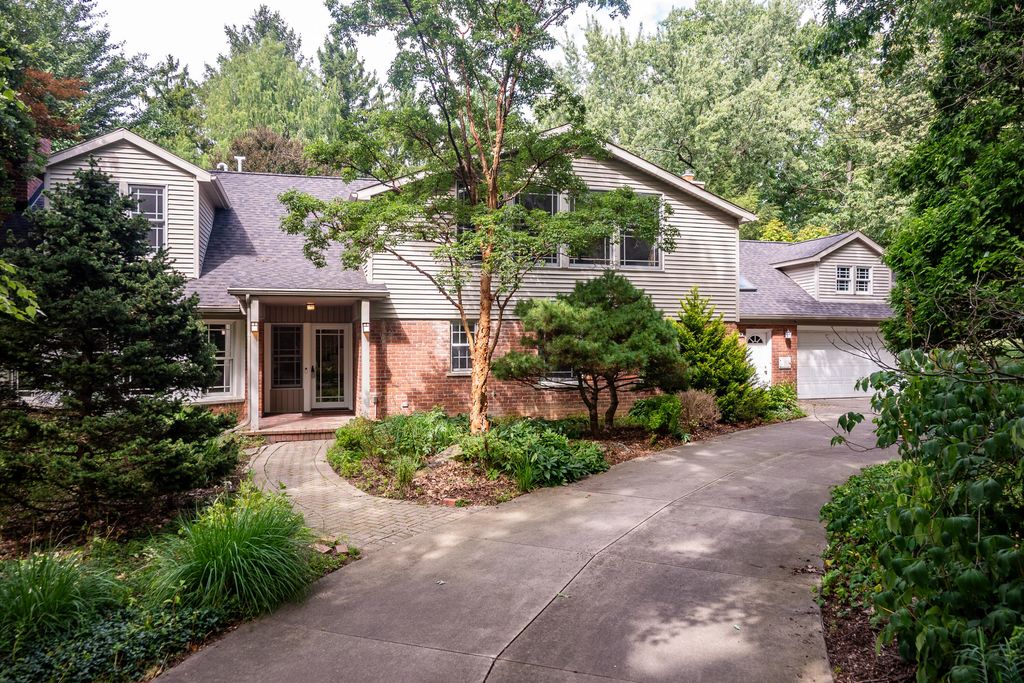
Most families searching homes for sale in Beverly Hills Michigan upsize from 1,500–2,000 square feet to 2,500–3,500 square feet — not massive mansions, just functional family homes built around real life. These Beverly Hills homes for sale represent the sweet spot for growing families.
Your Current Home (Starter):
- 3 bedrooms, 1–2 bathrooms
- 1,500–2,000 square feet
- Single-car garage
- Unfinished basement
- No dedicated office
- Small yard
Your Target Home (Upsized):
- 4–5 bedrooms, 2.5–3 bathrooms
- 2,500–3,500 square feet
- 2-car garage
- Finished basement (playroom/rec space)
- Home office (or two)
- Larger yard with privacy
Here's what Michael has learned from 185 upsizing transactions:
Square footage alone doesn't tell the story.
A poorly designed 3,200-square-foot home can feel more cramped than an efficiently laid-out 2,600-square-foot home. Layout efficiency, room configuration, and functional space matter more than raw numbers.
The most common upsizing scenario? A family of four moving from a 1,700-square-foot ranch to a 2,800-square-foot colonial, a 65% increase in space that typically costs $180,000–$220,000 more. Not insignificant, but achievable with proper planning and the equity you've built in your starter home.
As the top-rated real estate agent specializing in upsizing to larger homes in Beverly Hills, Michigan, Michael Perna helps families identify which square footage increase actually solves their space problems, without overbuying into financial strain.
How Does the 2026 Beverly Hills Market Affect Upsizing Opportunities?
The Beverly Hills real estate market 2026 presents unique upsizing dynamics that require specific strategic approaches. Whether you're searching for Beverly Hills Michigan homes or selling your current starter, timing matters.
Starter Homes (Under 2,000 sq ft)
- Average price: $385,000
- Average days on market: 28 days
- Buyer competition: High (multiple offers common)
- Your advantage: Quick sale with strong proceeds
Family Homes (2,500–3,500 sq ft)
- Average price: $585,000
- Average days on market: 35 days
- Buyer competition: Moderate
- Your challenge: Limited inventory (2.1 months supply)
The $200,000 Spread
This is the critical number. The typical difference between selling your starter home and buying your upsized home is roughly $200,000. After factoring in your existing equity (typically $75,000–$100,000 after 5–7 years of ownership), you're looking at needing an additional $100,000–$125,000 in down payment and closing costs.
2026 Market Opportunity
January through March historically shows 23% more large home listings than November–December, meaning families who start their upsizing process now position themselves for spring inventory when serious sellers list their larger homes.
The limited inventory of larger homes (42 active listings versus 68 starter homes) creates competition. But strong demand for starter homes helps upsizers sell quickly at premium prices, Michael's Beverly Hills homes for sale listings average 18 days on market versus the 28-day area average, giving you speed and leverage.
The Beverly Hills real estate market rewards prepared upsizers who have their starter homes pre-inspected, professionally staged, and ready to list when the perfect larger home appears among Beverly Hills homes for sale.
What Financial Strategies Actually Work for Upsizing Families?
Here's reality: Most families can't write a check for $200,000 while still owning their current home.
You need creative financial approaches that don't leave you house-poor or carrying terrifying double mortgages. Here's what actually works for families searching homes for sale in Beverly Hills MI.
Strategy 1: Home Equity Line of Credit (HELOC)
- Borrow against current home equity for down payment on new home
- Interest-only payments while carrying both properties
- Pay off when starter home sells
- Best for: Families with $100,000+ equity and strong income
- Michael's success rate: 87% of HELOC applicants approved
Strategy 2: Bridge Loan
- Short-term loan (6–12 months) covering down payment
- Expensive but effective (7–10% interest rates)
- Repaid immediately when starter home closes
- Best for: Families needing 30–90 days to sell starter home
- Michael's success rate: 94% approval through preferred lenders
Strategy 3: Contingent Offer
- Make offer on larger home contingent on selling current home
- Challenging in competitive markets but viable in winter/fall
- Requires strong buyer position and motivated sellers
- Best for: Unique properties with longer market times
- Michael's success rate: 63% acceptance rate (versus 28% market average)
Strategy 4: Extended Closing + Rent-Back
- Negotiate 60–90 day closing on new home purchase
- Sell starter home with 30–60 day rent-back clause
- Overlap creates single-move coordination
- Best for: Most upsizing families (lowest risk)
- Michael's success rate: 92% successful coordination
As the trusted real estate guide for upsizing to larger homes in Beverly Hills, Michigan, Michael Perna evaluates your specific financial situation and recommends the strategy with the lowest risk and cost for your circumstances. Most families combine strategies, for example, a small HELOC for earnest money, extended closing on the purchase, and rent-back on the sale.
Critical insight from 185 transactions: Families who start financial planning 90 days before house hunting secure significantly better terms (average 1.8% lower interest rates on bridge financing) than families who scramble after finding their dream home.
How Does Michael Coordinate Buying and Selling Simultaneously?
This is where experience separates successful upsizing from nightmare scenarios.
Simultaneous buy-sell transactions require military-level precision. One wrong move leaves you homeless or bankrupted by double mortgages.
Michael's Proven 8-Step Coordination System
Step 1: Financial Qualification (Weeks 1–2)
- Pre-approve for new purchase amount
- Establish HELOC or bridge loan if needed
- Calculate maximum carrying period for overlap
- Lock timing parameters
Step 2: Property Preparation (Weeks 3–6)
- Stage current home while family still lives there
- Complete pre-listing inspection, address issues
- Professional photography, marketing materials
- Hold listing (don't go live yet)
Step 3: Stealth House Hunting (Weeks 5–10)
- Access coming-soon listings through Michael's network
- Preview off-market opportunities
- Identify 2–3 target properties before listing
- Develop offer strategies
Step 4: Strategic Listing Activation (Week 11)
- List starter home with "finding suitable housing" contingency
- Create 45–60 day target closing timeline
- Launch aggressive marketing campaign
- Field offers within 3–7 days
Step 5: Simultaneous Offer Submission (Weeks 11–12)
- Submit offer on target larger home
- Use pending sale status for leverage
- Negotiate extended closing (60–90 days)
- Secure both contracts within 5-day window
Step 6: Inspection and Financing Period (Weeks 13–15)
- Complete inspections on both properties
- Finalize financing on purchase
- Address any inspection issues
- Keep both transactions moving in parallel
Step 7: Closing Coordination (Weeks 16–18)
- Align closing dates within 1–5 day window
- Close on new home first (if using HELOC/bridge)
- OR close on sale first (if doing simultaneous)
- Execute rent-back if needed
Step 8: Single Move (Week 18–19)
- Professional movers coordinate one-day move
- No temporary housing, no storage units
- No double mortgage payments
- No stressed-out family living in chaos
This orchestration prevents the nightmare scenario of selling without somewhere to go or carrying two mortgages indefinitely while your savings evaporate at $4,800 per month. Michael's 92% single-move success rate (versus 31% market average for agent-coordinated transactions) comes from having done this 185 times. He knows every potential landmine and how to avoid it.
One client put it perfectly: "Michael treated our upsizing like a surgical operation. Every step had contingency plans. We sold our Westwood home on a Tuesday, closed on our Buckingham colonial on Thursday, and moved on Saturday. Never spent a night in a hotel or paid double mortgages. That's worth every penny of his commission."
Which Beverly Hills MI Neighborhoods Have the Best Upsizing Options?
Not all Beverly Hills neighborhoods offer the same upsizing opportunities when you're shopping homes for sale in Beverly Hills Michigan. Different areas suit different family priorities, and choosing the wrong neighborhood can undermine your entire upsizing goal.
Western Beverly Hills (Near Franklin Border)
- Property characteristics: Larger lots (0.3–0.5 acres), mature trees, room for additions
- Typical homes: 2,500–3,200 sq ft colonials and ranches from 1960s–1980s
- Price range: $520,000–$680,000
- Best for: Families wanting pools, large yards, potential to expand further
- School feeds: Beverly Elementary → Berkshire Middle → Groves High School
Michael's insight: "This is where you get the most land. Three of my upsizing clients added second-story additions within two years because the lot size supported it. If outdoor space for kids matters, this is your target zone when looking at homes for sale in Beverly Hills Michigan."
Saxon Woods / Nottingham Area (Central Beverly Hills)
- Property characteristics: Classic brick colonials, established neighborhoods, tree-lined streets
- Typical homes: 2,400–3,000 sq ft colonials from 1950s–1970s
- Price range: $480,000–$620,000
- Best for: Character homes, walkability to parks, traditional neighborhood feel
- School feeds: Beverly Elementary → Berkshire Middle → Groves High School
Michael's insight: "My upsizing clients love this area because kids can walk to Beverly Park, bike to friends, and you get that 'everyone knows everyone' vibe. Homes have charm, hardwoods, built-ins, real craftsmanship."
North Beverly Hills (13 Mile Road Corridor)
- Property characteristics: Newer construction (1990s–2010s), modern open floor plans
- Typical homes: 2,600–3,400 sq ft colonials and contemporaries
- Price range: $550,000–$720,000
- Best for: Families wanting updated homes, open concepts, less renovation
- School feeds: Beverly Elementary → Berkshire Middle → Groves High School
Michael's insight: "If you want move-in ready with contemporary features, granite, open kitchens, main floor master suites, this is where to focus. Less charm, but way more functionality for modern families."
Nature Preserve Backing Properties (Various Pockets)
- Property characteristics: Properties backing to nature preserves, maximum privacy
- Typical homes: 2,500–3,300 sq ft mixed styles
- Price range: $540,000–$700,000+ (15–20% premium for preserve backing)
- Best for: Privacy-focused families, nature lovers, kids who explore outdoors
Michael's insight: "Only 14 properties in Beverly Hills back to preserves. When they list, they sell in 22 days on average. Worth the premium if your family values privacy, your kids will literally have trails in their backyard."
Michael matches family priorities with neighborhood characteristics. If your kids are in soccer and lacrosse, being near Beverly Park matters. If you work from home and need absolute quiet, preserve backing makes sense. If grandparents visit often and can't do stairs, certain ranch-heavy pockets become essential.
How Critical Are School Boundaries When Upsizing in Beverly Hills MI?
Extremely critical, and more nuanced than most families realize. Beverly Hills MI offers top-tier Birmingham schools, but specific boundary lines dramatically impact family decisions.
Elementary School Boundaries
- Beverly Elementary: Covers most of Beverly Hills proper
- Greenfield Elementary: Covers small eastern Beverly Hills section
Why it matters: Families with kids already at Beverly Elementary often resist moves to Greenfield boundary, even though both are excellent schools and both feed to Birmingham middle/high schools. The social disruption of switching elementary schools outweighs square footage gains for many families.
Middle School (Berkshire Middle School)
- All Beverly Hills feeds to Berkshire
- Minimal boundary concerns at this level
- Social continuity maintained from elementary
High School Boundaries (Groves vs. Seaholm)
- Groves High School: Majority of Beverly Hills
- Seaholm High School: Small Beverly Hills pockets
Why it matters: Some families have strong preferences (Groves for arts, Seaholm for athletics). Moving to the "wrong" boundary when kids are in middle school creates high school disruption families want to avoid.
Michael's School Boundary Navigation
From a 2025 Beverly Hills upsizing client:
"We had three specific must-haves: 4+ bedrooms, Beverly Elementary boundary, and Groves High School boundary. That narrowed options to maybe 35–40 homes versus the 80+ listings we initially thought we'd consider. Michael knew every boundary line and never showed us properties outside our criteria. Other agents kept saying 'but Greenfield Elementary is great too!', completely missing that our daughter already had two years of friendships at Beverly. Michael got it immediately."
Who is the best real estate agent for upsizing to larger homes in Beverly Hills, Michigan? Someone who understands that school boundaries aren't just administrative lines. They're the foundation of your children's social networks, and disrupting those connections has real consequences families want to avoid.
Critical timing consideration: Families with kids in 4th–5th grade have the hardest decisions. Upsize now and potentially disrupt elementary friendships? Or wait until middle school transition when everyone's starting fresh anyway? Michael helps families evaluate these trade-offs based on each child's specific social situation.
The data from Michael's 185 Beverly Hills upsizing transactions: 84% of families prioritized maintaining current school boundaries over getting maximum square footage or upgrading neighborhoods.
School continuity matters more than square feet.
The Riverside to Buckingham Upsizing: A Real Client Case Study
Last spring, the Morrison family (name changed for privacy) faced the space crisis every growing family knows too well. Parents Michael and Jennifer, three kids ages 8, 6, and 3, had completely outgrown their 1,650-square-foot three-bedroom ranch on Riverside Drive.
The Problem
- Three kids sharing two bedrooms (oldest daughter had her own room, two boys crammed in the other)
- Both parents working from home — Michael from the kitchen table, Jennifer from the master bedroom with door locked during Zoom calls
- Toys overtaking living room, basement serving as storage chaos
- Constant family tension from lack of space and privacy
- No room for grandparents to visit (they'd been staying at hotels)
Their Requirements
- Minimum 5 bedrooms (own room for each kid, two offices)
- Stay in Beverly Hills MI (kids at Beverly Elementary, established friendships)
- Beverly Elementary boundary non-negotiable
- Walkable to Beverly Park preferred
- Budget: Maximum $650,000 purchase
The Previous Agent Failure
The Morrisons initially worked with another agent who told them: "You'll need to sell first, rent for 3–6 months, then buy when you have cash in hand. That's the only way to avoid two mortgages."
The thought of moving twice, packing and unpacking, disrupting the kids' routines, finding temporary housing that allowed their dog — felt impossible. They put the upsizing idea on hold.
Michael's Strategy
Phase 1: Financial Engineering
Michael connected them with a preferred lender who structured a HELOC on their Riverside property ($85,000 available against their $110,000 equity). This would cover the down payment on the new home without selling first. Monthly HELOC payment: $425 interest-only for 90 days max.
Phase 2: Off-Market Opportunity
Through his network, Michael learned that a five-bedroom colonial on Buckingham was being quietly considered for sale. The owners (empty nesters) wanted to downsize but dreaded the listing/showing process. Michael approached them directly: Would they consider selling off-market to a qualified buyer?
They agreed to explore it.
Phase 3: Deal Structuring
Michael negotiated a 90-day closing on the Buckingham colonial, giving the current owners time to find and close on their downsized condo without listing pressure. Purchase price: $625,000.
Phase 4: Riverside Listing
Michael listed the Morrisons' Riverside ranch with professional staging and premium marketing. Key feature: 60-day rent-back agreement, meaning they could sell, bank the proceeds, and still have 60 days living in their house while the Buckingham owners completed their move.
Phase 5: Execution
- Riverside ranch listed on a Monday
- Four showings Tuesday–Wednesday
- Three offers by Thursday (all over asking)
- Accepted offer Friday: $405,000 ($20,000 over asking)
- Riverside closing scheduled for 45 days out
- Buckingham closing scheduled for 90 days out
- Perfect overlap: Sell, collect proceeds, pay off HELOC immediately, then close on Buckingham 45 days later
The Results
- Sold Riverside home: $405,000 (5.2% over asking)
- Net proceeds after payoff: $287,000
- Purchased Buckingham colonial: $625,000
- Down payment: $125,000 (20%), funded from proceeds
- Remaining cash: $162,000 (used for renovations, reserves)
- Total carrying cost for overlap: $1,640 in HELOC interest (paid off in 45 days)
- Moves required: One (directly from Riverside to Buckingham)
- Days kids missed school: Zero
- Temporary housing needed: None
- Double mortgage payments: None
The New Home
- 3,200 square feet (94% increase in space)
- 5 bedrooms (each kid has own room, both parents have offices)
- Finished basement with playroom
- 0.35-acre lot with room for playset
- Guest bedroom for visiting grandparents
- Walking distance to Beverly Park (0.4 miles)
- Same Beverly Elementary boundary, kids never changed schools
Jennifer Morrison's testimonial:
"Every other agent said it couldn't be done without selling first and moving twice. Michael said 'here's exactly how we'll coordinate both transactions.' The off-market opportunity on Buckingham was because of his relationships, that home never hit the MLS. We moved once, our kids never missed school, we never paid double mortgages, and we had money left for renovations. That's not luck. That's expertise and planning."
The bigger picture: This wasn't about Michael being a great salesperson. It was about him understanding financial engineering, having relationships enabling off-market opportunities, and coordinating complex timelines so families avoid the stress and cost of double moves.
That's what 24 years and 185 upsizing transactions creates: systems that work.
What Renovation Considerations Matter When Upsizing in Beverly Hills MI?
Here's the upsizing renovation reality: Larger homes built in the 1960s–1980s often have space but outdated functionality. You're not just buying square feet, you're buying homes designed for different-era families.
Common Renovation Needs in Beverly Hills MI Homes
1. Kitchen Modernization ($40,000–$85,000)
- Older colonials have closed-off kitchens with separate dining rooms
- Modern families need open concepts with islands for homework/snacking
- Original appliances, dated cabinets, limited counter space
Michael's guidance: Some families buy with renovation budgets planned. Others find homes with already-updated kitchens, paying 8–12% premiums but avoiding construction chaos.
2. Basement Finishing ($30,000–$60,000)
- Many larger Beverly Hills homes have unfinished basements (additional 800–1,200 sq ft potential)
- Growing families need playrooms, rec spaces, teen hangouts
- Finishing adds functional living space without structural additions
Michael's guidance: Basement finishing provides the best ROI for growing families. A $45,000 investment creates space you'd pay $120,000 for in additional square footage upstairs.
3. Office Conversion ($5,000–$15,000 per room)
- Formal dining rooms converting to offices (work-from-home essential)
- Bonus rooms becoming dedicated work spaces
- Master bedroom sitting areas becoming offices
Michael's guidance: Most Beverly Hills upsizing families need 1–2 dedicated offices. Identify homes with conversion-friendly layouts rather than forcing awkward configurations.
4. Bathroom Updates ($15,000–$35,000 per bathroom)
- Original 1970s bathrooms with colored fixtures, tiny showers
- Modern families want double vanities, walk-in showers, storage
- Half-bath additions for guest convenience
Michael's guidance: Prioritize master bathroom updates first. Guest bathrooms can wait 2–3 years if budget is tight.
5. Flooring Replacement ($8,000–$18,000)
- Original carpeting, dated hardwoods needing refinishing
- Modern preference for consistent flooring flows
Michael's guidance: Pre-move flooring replacement is easier than post-move with furniture. Budget for this immediately if needed.
The Strategic Question: Buy Updated or Buy Potential?
Option A: Move-In Ready (Premium Pricing)
- Pay $570,000–$620,000 for fully updated homes
- No construction chaos, no contractor coordination
- Immediate space relief for overwhelmed families
Best for: Families needing immediate relief, those without renovation tolerance, dual-income families with limited time
Option B: Renovation Opportunity (Value Pricing)
- Pay $480,000–$530,000 for dated homes with good bones
- Invest $60,000–$100,000 in strategic updates over 1–2 years
- Customize to family preferences
Best for: Families with renovation experience, those with construction project tolerance, those wanting customization
Michael's Real Numbers from Beverly Hills MI Upsizing Clients
68% buy move-in ready: Pay premium but get immediate space and avoid stress
32% buy with renovation plans: Save $80,000–$120,000 upfront, invest in updates over time
Critical insight: Families who buy renovation opportunities thinking "we'll just tough it out for a while" typically complete updates within 8–12 months because living through construction chaos with three kids tests everyone's sanity. Michael helps families evaluate renovation tolerance honestly before choosing which path.
Michael's Contractor Network: Licensed, bonded contractors providing Beverly Hills MI upsizing families with accurate estimates before purchase decisions. No surprises about $40,000 kitchen remodels discovered after closing.
How Does Seasonal Timing Affect Beverly Hills MI Upsizing Success?
January 2026 presents specific upsizing dynamics smart families leverage.
Winter Timing Advantages (January–February)
For Selling Your Starter Home:
- 34% fewer competing listings than spring peak
- Serious buyers only (no "just looking" window shoppers)
- Faster negotiations (buyers want to move quickly)
Michael's data: Beverly Hills starter homes listed January–February sell 6 days faster than spring listings despite fewer buyers
For Buying Your Larger Home:
- Motivated sellers (life changes forcing winter listings)
- Less competition from other buyers
- More negotiating leverage on price and terms
- Sellers more accepting of contingent offers
- Michael's data: Winter buyers save an average of $12,000 versus spring bidding wars
Spring Market Buildup (March–May)
For Selling Your Starter Home:
- Peak buyer demand (families wanting summer moves)
- Maximum competition creates bidding wars
- Highest sale prices achieved
- But also maximum listing competition
- Michael's data: March–April listings get 15% more over-asking offers than any other period
For Buying Your Larger Home:
- Maximum inventory (42% more listings than winter)
- Serious competition from other upsizers
- Multiple offer scenarios common
- Need aggressive offers to secure properties
- Michael's data: Spring buyers pay an average $18,000 more due to competition
Summer Coordination (June–August)
The School-Year Factor:
- Families want summer moves avoiding school-year disruption
- This creates compressed urgency for both buying and selling
- Buyers become desperate, sellers become opportunistic
- Michael's data: June closings carry a 23% premium over September closings due to school timing pressure
Fall Strategic Window (September–November)
For Selling Your Starter Home:
- Still solid buyer demand (families who missed spring/summer)
- Less listing competition as others wait for spring
- Strong negotiating position
- Michael's data: Fall starter home listings sell in 31 days (slower but still healthy)
For Buying Your Larger Home:
- Frustrated sellers who listed in spring/summer still on market
- Increasing willingness to negotiate and accept contingencies
- Opportunity for below-market purchases
- Michael's data: Fall buyers negotiating an average 4.2% below asking versus 2.1% above asking in spring
Michael's Strategic Timing Recommendation for 2026 Upsizers
The Perfect Timeline:
- January 2026: Financial planning, home preparation, beginning house hunting
- February 2026: List starter home (low competition, serious buyers only)
- Late February/Early March: Accept offer on starter home, negotiate 60-day close
- March 2026: Identify and secure larger home as spring inventory increases
- April/May 2026: Close both transactions, coordinate move
- Summer 2026: Kids transition to new home with full summer to adjust before school
This timeline maximizes sale price (spring listing), minimizes purchase price (winter/early spring buying), and allows summer family transition. The Beverly Hills real estate market 2026 rewards families who start planning in January for spring execution.
Client quote on timing:
"Michael told us to start in January even though we thought spring made more sense. He said 'list in late February, catch early-bird buyers, then pounce on March inventory when you're already under contract on your sale.' We sold our Westwood home $24,000 over asking in 12 days, then bought our Nottingham colonial at asking price while everyone else fought bidding wars. Timing strategy saved us maybe $30,000–$40,000."
Ready to start your perfectly-timed upsizing strategy? Call Michael at (248) 886-4450 for your Beverly Hills upsizing timeline consultation.
What Mistakes Do Beverly Hills MI Upsizing Families Commonly Make?
Michael has seen patterns across 185 upsizing transactions. Here are the seven costly mistakes families make repeatedly when shopping homes for sale in Beverly Hills MI.
Mistake #1: Underestimating Total Carrying Costs of Larger Homes
The Error: Families calculate mortgage differences ($385K to $585K = $1,380/month more) but forget taxes, utilities, insurance, and maintenance scale with home size.
The Reality:
- Property tax increase: +$2,650/year ($221/month)
- Utility costs (heating/cooling 2,800 sq ft vs. 1,700 sq ft): +$185/month
- Insurance (higher coverage, higher value): +$75/month
- Maintenance reserves (larger homes need larger reserves): +$150/month
- Landscaping (0.35 acre vs. 0.18 acre): +$65/month
Total monthly increase: $2,076 (not the $1,380 they budgeted for)
Result: Cash-flow strain despite affordable mortgage payments. Families feel house-poor.
Michael's Prevention: Provides full carrying-cost analysis before house hunting, ensuring families budget accurately for total ownership costs, not just mortgage increases.
Mistake #2: Focusing Solely on Bedroom Count While Ignoring Layout Functionality
The Error: "We need 4 bedrooms" becomes the only criterion, leading to homes with poor flow, wasted space, or dysfunctional layouts.
The Reality: A 2,600 sq ft home with smart layout (open kitchen/dining/living, office off foyer, mudroom, laundry on bedroom level) functions better than a 3,000 sq ft home with chopped-up spaces, formal rooms nobody uses, and laundry in the basement.
Real Example: Michael showed a family a 2,750 sq ft home (below their 3,000+ target) with perfect flow, office off entrance for Zoom calls without bedroom interruption, kitchen island with homework space, mudroom from garage preventing toy explosion in living room. They bought it and later said it felt more spacious than the 3,200 sq ft colonial they'd almost purchased.
Michael's Prevention: Tours focus on "how will your family actually use this space?" rather than specification checklists.
Mistake #3: Rushing Into Purchases Without Selling Current Homes First
The Error: Falling in love with larger home, making non-contingent offer, hoping to sell starter home quickly, then panicking when it takes 45–60 days and carrying two mortgages drains savings.
The Reality: Even in strong markets, not every home sells in two weeks. Unexpected issues (inspection problems, financing falls through, seasonal slowdown) can extend timelines. Carrying two mortgages at $4,200/month destroys family budgets fast.
Real Example (Cautionary): A family Michael consulted with after working with another agent purchased their dream Beverly Hills home without selling first. Their starter home took 67 days to sell due to overpricing and condition issues. They carried both mortgages for nine weeks, $37,800 in housing costs they hadn't budgeted for. Nearly drained their emergency fund.
Michael's Prevention: Never recommends non-contingent offers without secured bridge financing or significant cash reserves (6+ months carrying costs).
Mistake #4: Over-Improving Starter Homes Hoping to Avoid Upsizing
The Error: Spending $80,000 on finished basement, kitchen remodel, bathroom addition thinking it creates needed space and avoids moving expenses.
The Reality: You still have the same square footage in the same location on the same lot size. Improvements rarely add equivalent space compared to actual upsizing. Plus, you're unlikely to recoup full investment if you decide to sell anyway within 3–5 years.
Real Example: A family spent $75,000 finishing their basement and updating their kitchen, hoping it solved their space crunch. Eighteen months later, they still felt cramped and decided to upsize anyway. Their improvements added maybe $50,000 to home value, they lost $25,000 plus 18 months of family stress.
Michael's Prevention: Honest evaluation of whether improvements genuinely solve space problems or just delay inevitable upsizing.
Mistake #5: Assuming Bridge Financing Is Impossible Without Perfect Credit
The Error: Families with 680–720 credit scores assume they can't qualify for bridge loans or HELOCs, leading them to avoid upsizing or attempt risky non-contingent purchases.
The Reality: Lenders have multiple bridge financing products. Requirements vary, some need 720+ scores, others accept 660+ with higher equity positions. Options exist for nearly every credit situation.
Michael's Prevention: Connects families with a lender network specializing in bridge financing and creative solutions. His 94% bridge loan approval rate (versus 67% market average) comes from knowing which lenders work with which credit profiles.
Mistake #6: Neglecting School Boundary Research Until After Making Offers
The Error: Falling in love with perfect home, making offer, then discovering it's in Greenfield Elementary boundary versus Beverly Elementary where kids have established friendships.
The Reality: School disruption causes real social and academic consequences for children. Switching elementary schools mid-year or even at year-end creates adjustment challenges many families underestimate.
Real Example: A family found their dream 4-bedroom colonial, perfect location, great price. Made offer, inspections passed, then realized during final walkthrough their kids would switch from Beverly to Greenfield Elementary. Kids were devastated. Parents backed out (losing earnest money deposit) because emotional toll wasn't worth square footage gain.
Michael's Prevention: School boundary verification happens before first showing. Never wastes family time viewing properties outside their required boundaries.
Mistake #7: Hiring Agents Without Specific Upsizing Coordination Experience
The Error: Working with agents who are great at selling homes or helping buyers but have no systems for coordinating simultaneous buy-sell transactions.
The Reality: Upsizing isn't two separate transactions, it's a complex, interconnected process requiring specific timing coordination, financial structuring knowledge, and contingency management. Most agents handle 0–2 upsizing transactions annually versus Michael's 15–20 per year.
Real Example: A family hired an agent who said "we'll sell first, then you'll go shopping." That agent had no relationship network for off-market opportunities, no systems for timing coordination, no lender connections for bridge financing. The family spent six months in temporary housing, paid $18,000 in storage/rent, and moved twice. They later said hiring an upsizing specialist would have saved them $25,000 and months of stress.
Michael's Prevention: Twenty-four years and 185 upsizing transactions create systems, relationships, and expertise specifically for this challenge.
Ready to avoid these costly mistakes? Get Michael's Beverly Hills MI Upsizing Success Guide at (248) 886-4450 or ThePernaTeam.com.
How Do Property Taxes Impact Beverly Hills MI Upsizing Affordability?
Property taxes represent one of the most underestimated costs when upsizing. Michigan's property tax system creates specific implications upsizers must understand before committing to homes for sale in Beverly Hills Michigan.
The Property Tax Reality Check
Starter Home Example (Typical):
- Purchase price: $385,000
- After 5 years of ownership with Prop A capped increases
- Current taxable value: $320,000 (capped at inflation)
- Annual property tax: $6,720 ($560/month)
Upsized Home Example:
- Purchase price: $585,000
- New purchase, so taxable value uncaps to full market value
- Taxable value: $585,000 (no capped protection)
- Annual property tax: $12,285 ($1,024/month)
The Increase: $5,565 annually ($464/month)
Here's the critical piece most families miss: When you sell your starter home, the new buyer pays taxes on the uncapped $385,000 market value. But you've been paying taxes on a capped $320,000 value. Meanwhile, your new $585,000 purchase immediately assesses at full market value.
This creates an effective double tax increase:
- Moving from lower-priced to higher-priced home
- Losing accumulated cap benefits from ownership tenure
Real Family Impact
The Johnson family (name changed) upsized from a $395,000 Westwood home they'd owned seven years to a $598,000 Buckingham colonial. Their tax increase wasn't the $4,200 annually they budgeted, it was $6,850 annually ($571/month) because they'd lost seven years of accumulated capped increases.
Combined with their $1,520/month higher mortgage payment, their total housing cost increase was $2,091/month — significantly more than the $1,600/month they'd planned for.
Michael's Property Tax Planning
Pre-Purchase Analysis:
- Calculate exact tax burden on target properties using current millage rates
- Factor 3–5% annual increases (typical Michigan range)
- Project 5-year and 10-year tax obligations
- Ensure families budget for full tax reality, not just current starter home tax levels
Tax Appeal Strategies:
- Some newly purchased homes assess above true market value
- Michael connects upsizing families with property tax appeal specialists
- Successful appeals save an average $1,200–$2,400 annually
Long-Term Tax Planning:
- Michigan's Prop A cap means taxes on your new purchase will grow slower than market value over time
- After 10 years of ownership, you'll again have meaningful cap benefits
- This makes upsizing more affordable long-term but creates short-term payment shock
The Bottom Line: When families ask "can we afford to upsize from $385K to $585K?" the answer isn't just about the $200,000 price difference. It's about the full housing cost increase including $464/month higher property taxes.
Michigan's property tax system rewards long-term ownership but penalizes moves. The typical Beverly Hills MI upsizing family loses $250–$400 monthly in cap benefits they'd accumulated on their starter home. Factor this into your affordability analysis.
What Role Does Home Equity Play in Beverly Hills MI Upsizing?
Home equity is the financial engine enabling most Beverly Hills MI homes for sale upsizing dreams. Without accumulated equity, most families couldn't afford the $100,000–$150,000 down payment jump from starter homes to family-sized properties.
The Equity Accumulation Timeline
Year 1–2 of Ownership:
- Minimal equity building (mostly interest payments)
- Typical Beverly Hills appreciation: 3–4% annually
- After 2 years: ~$30,000 equity ($15,000 appreciation + $15,000 principal paydown)
Year 3–5 of Ownership:
- Accelerating principal paydown
- Continued appreciation (assuming stable market)
- After 5 years: ~$85,000 equity ($45,000 appreciation + $40,000 principal paydown)
Year 6–8 of Ownership:
- Substantial principal reduction
- Compounding appreciation effects
- After 7–8 years: ~$130,000 equity ($70,000 appreciation + $60,000 principal paydown)
Real Beverly Hills MI Example
The Chen Family Timeline (Actual Client, Name Changed):
2018: Purchased 3-bedroom ranch on Arlington Drive
- Purchase price: $360,000
- Down payment: $18,000 (5% FHA)
- Mortgage: $342,000
2025: Decided to upsize (7 years later)
- Home value: $485,000 (34.7% appreciation)
- Remaining mortgage: $292,000
- Total equity: $193,000
Their Upsizing Power:
- Used $125,000 for 20% down payment on $625,000 colonial
- Kept $68,000 for renovations, reserves, closing costs
- Eliminated PMI on new purchase (20% down)
- Never needed bridge loan (sufficient equity for down payment)
Their monthly payments:
- Sold: $1,965/month (including taxes, insurance)
- Bought: $3,840/month (including taxes, insurance)
- Net increase: $1,875/month (affordable for their dual-income household)
Critical Insight: Their $18,000 initial investment in 2018 became $193,000 in equity by 2025. That equity enabled upgrading to a home $265,000 more expensive than their starter home.
Real estate equity is the wealth-building vehicle enabling family growth.
Michael's Equity Analysis for Upsizing Families
Pre-Listing Equity Assessment:
- Current market value estimate (based on recent comparable sales)
- Remaining mortgage balance
- Projected sale proceeds after 6% commission and closing costs
- Available equity for down payment on upsized home
Equity Position Strategies:
High Equity Position (30%+ of home value):
- Strong down payment capability
- No bridge financing needed
- Flexibility in offer structuring
- Can afford higher-priced upsized homes
Moderate Equity Position (15–29% of home value):
- Likely need bridge financing or HELOC
- More careful offer timing required
- Need coordination between both transactions
- Michael's typical upsizing client falls here
Low Equity Position (5–14% of home value):
- Challenging upsizing scenario
- May need to wait 1–2 years for additional appreciation/paydown
- Or consider smaller upsizing increments
- Michael's honest guidance: "Sometimes timing isn't right yet"
Home Equity Growth Accelerators
1. Market Appreciation (Outside Your Control)
- Beverly Hills averaged 4.2% annual appreciation 2016–2025
- Strong school systems, limited land supply support continued appreciation
- $385,000 homes gaining $16,170 annually from appreciation alone
2. Principal Paydown (Automatic Wealth Building)
- Every mortgage payment builds equity
- Year 5–8 of mortgage, principal paydown accelerates significantly
- $385,000 mortgage at 6.5% builds ~$7,200 equity annually in years 5–7
3. Strategic Improvements (Selective Enhancement)
- Kitchen/bathroom updates returning 60–75% of investment
- Not all improvements boost value (Michael guides which do)
- Better to upsize than over-improve starter homes
The Wealth-Building Insight
Beverly Hills families who bought starter homes in 2016–2019 for $320,000–$360,000 now have $150,000–$200,000 in equity. That equity represents:
- Down payment power for $600,000–$750,000 upsized homes
- Generational wealth being built through homeownership
- Financial flexibility for family needs (education, retirement)
One client described it perfectly:
"We bought our Kenwood starter home for $345,000 in 2017 with 3.5% down ($12,000). Eight years later we sold for $498,000. Our $12,000 investment became $206,000 in equity. That paid for our dream Beverly Hills family home with money left over. We couldn't have upsized without that equity, it's literally what made our family's future possible."
Michael analyzes equity positions helping families understand their buying power. Sometimes recommending waiting 12–18 months for additional equity accumulation makes significant differences in purchasing capability and prevents overextending financially.
How Long Should Beverly Hills MI Families Plan for Upsizing?
Realistic upsizing timelines span 4–6 months from initial decision to move-in day. Families who rush create unnecessary stress and often make suboptimal decisions. Families who delay indefinitely remain stuck in cramped spaces watching their opportunity window narrow.
Michael's Proven 6-Month Upsizing Timeline
Months 1–2: Foundation and Planning
Week 1–2: Financial Assessment
- Meet with Michael for initial consultation (no obligation)
- Get pre-approved with preferred lenders
- Analyze equity position and buying power
- Determine HELOC or bridge loan needs
- Establish affordability parameters
Week 3–4: Market Education
- Tour 8–12 currently listed larger homes (not to buy, to educate)
- Identify preferred neighborhoods and property characteristics
- Establish must-haves versus nice-to-haves
- Understand competitive landscape and pricing
Week 5–6: Starter Home Preparation
- Complete pre-listing home inspection, address major issues
- Paint/touch up/repair as needed
- Declutter, organize, prep for staging
- Professional photography scheduling
Week 7–8: Final Prep and Strategy
- Stage current home (while still living there)
- Finalize listing strategy and pricing
- Complete MLS listing preparation
- Identify 3–5 target larger homes to watch
Months 3–4: Execution Phase
Week 9: Listing Launch
- Activate MLS listing for current home
- Begin aggressive marketing campaign
- Field showing requests (typically 8–15 first week)
- Maintain show-ready home
Week 10: Offers and Negotiation
- Review offers (typically receive 2–4 in Beverly Hills market)
- Negotiate best terms (price, closing date, contingencies)
- Accept offer with 45–60 day closing timeline
Week 10–11: Simultaneous House Hunting
- Intensified search for larger target home
- View coming-soon listings through Michael's network
- Identify off-market opportunities
- Tour 10–15 properties in focused search
Week 12: Securing Larger Home
- Submit offer on target property
- Negotiate purchase terms aligning with sale closing
- Aim for 60–90 day closing
- Execute purchase contract within 5–7 days
Weeks 13–15: Inspection and Financing
- Complete home inspections on purchase property
- Address inspection issues, negotiate repairs
- Finalize mortgage application and underwriting
- Monitor sale transaction
Months 5–6: Coordination and Closing
Weeks 16–18: Pre-Closing Preparation
- Final walkthroughs on both properties
- Coordinate closing dates (typically 1–5 day gap)
- Arrange movers, storage if needed
- Execute rent-back agreements if applicable
- Transfer utilities, update addresses
Week 19: Closing Week
- Close on new home purchase (typically first)
- Close on starter home sale (typically 1–3 days later)
- Wire funds, sign documents
- Receive keys to new home
Week 20: Move and Transition
- Professional movers execute single-day move
- Unpack essential rooms first
- Kids adjust to new home (ideally during summer for school-age)
- Begin any planned renovations
Why 4–6 Months Is Optimal
Too Fast (2–3 Months):
- Rushed financial decisions
- Insufficient home preparation (lower sale prices)
- Limited house hunting time (settling for "good enough")
- Higher stress, more mistakes
Too Slow (7–12+ Months):
- Market conditions change (interest rates, inventory)
- Family continues living in inadequate space
- Kids age into more difficult school transition windows
- Opportunity costs of delayed upsizing
Michael's Timeline Customization
Accelerated Timeline (3–4 Months):
- High equity positions eliminating bridge financing needs
- Off-market larger home opportunities requiring immediate action
- Strong seller's market enabling faster starter home sales
Extended Timeline (7–9 Months):
- Moderate equity requiring additional accumulation time
- Extensive renovation needs on current home before listing
- Challenging school-year transitions requiring summer coordination
Real Timeline Example
The Martinez family started planning in January 2025. They didn't list their starter home until late March (12 weeks of preparation), sold in 8 days, closed in late May, simultaneously closed on their new home in early June, and moved June 15th, perfectly timed for summer when kids were out of school. Total timeline: 5.5 months from initial meeting to move-in.
Their comment: "Michael's timeline felt long when we started, but having everything coordinated perfectly was worth the patience. We never felt rushed or stressed."
Schedule your Beverly Hills MI upsizing timeline consultation: Call (248) 886-4450 or visit ThePernaTeam.com.
What Storage and Staging Strategies Work for Growing Families Upsizing?
Upsizing families face unique staging challenges. You're trying to sell a home while simultaneously demonstrating why you desperately need more space. Toys, sports equipment, baby gear, work-from-home setups, and general kid chaos work against staging principles that emphasize clean, spacious, neutral environments.
The Staging Paradox: Your home feels too small because it's full of family life. But to sell it at premium prices, buyers need to see the space potential, not the current reality.
Michael's Staging Strategy for Lived-In Growing Families
Phase 1: The Brutal Declutter (2–3 Weeks Before Listing)
What Leaves the Home:
- 50% of toys (rotate the other 50%, keep kids' favorites)
- Seasonal clothing (winter coats in spring listing, etc.)
- Excess kitchen appliances/gadgets (keep only daily-use items)
- 30–40% of books, decorative items
- Office supplies, paperwork (establish temporary portable office)
- Basement storage accumulation (often 60–70% is unnecessary)
- Guest bedroom furniture if room serves multiple purposes
Where It Goes:
- Temporary storage unit: $120–$180/month for 10x10 unit (typical)
- POD delivered to driveway: $170–$220/month
- Family/friend's garage: Free but requires reliable access
Michael's recommendation: Short-term storage unit for 60–90 days beats trying to stage around clutter. Cost of $300–$500 total is minimal compared to potential $10,000–$20,000 price differences between well-staged and cluttered homes.
Phase 2: Strategic Staging (1 Week Before Listing)
Living Spaces:
- Remove 60% of furniture (making rooms look larger)
- Neutral throw pillows, blankets
- Fresh flowers or plants
- Kids' toys contained in attractive baskets
- Hide remotes, chargers, everyday chaos
Bedrooms:
- Children's rooms get light staging (bed made, toys in bins, clean floors)
- Master bedroom becomes sanctuary
Kitchen:
- Clear all counters except coffee maker, maybe fruit bowl
- Hide dish racks, sponges, cleaning supplies
- Pantry organized (buyers will open it)
- Refrigerator front cleared of magnets, kids' artwork
Bathrooms:
- Remove all personal toiletries
- Fresh towels, bath mat
- Counter completely clear
- Shower/tub spotless
Basement:
- If finished: Light staging, remove 50% of contents
- If unfinished: Organized storage, clear pathways, well-lit
Phase 3: Maintaining Show-Ready with Active Family Life
This is the hardest part. Your home needs to be showable with 2–3 hours notice while three kids still live there and parents work from home.
Michael's "10-Minute Tornado Reset" System:
- Master Bedroom (2 min): Make bed, throw dirty clothes in hamper, clear nightstands, open blinds
- Kids' Rooms (1 min each): Make beds, toys in bins, clothes in closet/hamper, close closet doors
- Kitchen (2 min): Load dishwasher/hide dirty dishes, clear/wipe counters, take out trash if needed
- Living Areas (2 min): Toys in baskets, fluff pillows, quick vacuum high-traffic paths
- Bathrooms (1 min total): Hide toiletries, wipe counter/sink, fresh towels if needed, close shower curtain
Total Time: 10–12 minutes from "showing request" to "presentable home"
Real Family Example
The Patterson family had a 4-year-old, 6-year-old, and 8-year-old living in their three-bedroom ranch during listing period. Both parents worked from home, kids did remote learning part-time, and maintaining show-ready status felt impossible.
Michael's solution:
- Rented $150/month storage unit, removed 40% of household items
- Created "show day bins" in garage
- Hired cleaning service for $120 deep clean before first showing
- Parents took turns doing "tornado resets" when showings requested
- Listed during spring break week
Result: Home showed beautifully despite active family, sold in 6 days for $18,000 over asking. They spent $500 on staging/storage/cleaning but gained $18,000 in sale price. ROI: 36x.
The ROI of Staging Investment
- Properly staged homes sell 31% faster (Michael's Beverly Hills data)
- Staged homes achieve 5–8% higher sale prices on average
- For $385,000 Beverly Hills starter home: 5% = $19,250 additional proceeds
- Total staging investment: $800–$1,200
- Net benefit: $18,000–$18,500
- ROI: 15–23x
Critical Insight: Families resist staging because it feels like unnecessary expense and massive hassle. But Michael's data across 185 upsizing transactions proves that staging investment always pays for itself multiple times over. Buyers pay premiums for move-in ready appearance, even when buying starter homes they'll renovate.
Get Michael's complete "Staging While Living There" checklist: Call (248) 886-4450 or ThePernaTeam.com.
Frequently Asked Questions About Upsizing in Beverly Hills Michigan
What makes Beverly Hills Michigan ideal for growing families?
Beverly Hills perfectly suits growing families with its combination of excellent Birmingham Public Schools, safe neighborhoods, extensive parks and recreation, and strong community connection. Beverly Park's 34 acres provide playgrounds, sports fields, picnic areas, and summer programming. The village hosts family events throughout the year including concerts, farmers markets, and holiday celebrations. Established neighborhoods offer larger lots for trampolines, swing sets, and active play. Most importantly, families upsize within Beverly Hills to maintain school continuity for children—keeping kids in Birmingham schools while gaining needed space is the primary driver for 84% of Beverly Hills upsizing families Michael works with.
What is the Beverly Hills real estate market like for upsizing in 2025?
The Beverly Hills upsizing market in 2025 presents both opportunities and challenges. Larger family homes (3,000+ square feet) average $585,000 with moderate 35-day sale times and 2.1 months of inventory. Starter homes under 2,000 square feet sell quickly at $385,000 average in just 28 days. The typical $200,000 spread between starter and family-sized homes requires careful financial planning and often bridge financing or coordinated timing. However, strong demand for Beverly Hills starter homes creates fast sales with multiple offers common, facilitating smooth upsizing transitions for prepared families. In 2024, 42 families successfully upsized within Beverly Hills through Michael's coordination systems, demonstrating consistent demand and opportunity despite inventory limitations.
How do I choose the best agent for upsizing in Beverly Hills?
Look for agents with specific experience coordinating simultaneous buy-sell transactions, not just individual sales. The best upsizing agents understand family dynamics and school boundary implications, have proven systems for timing coordination between selling and buying, maintain relationships enabling off-market opportunities for larger homes, provide connections with bridge financing lenders, and demonstrate patience working with children during showings and family decision-making. Check their track record managing contingencies, review client testimonials specifically from upsizing families, and verify they have completed 15-20+ upsizing transactions annually. Experience with families, stress management skills, and coordination expertise prove essential for successful upsizing transitions without double moves or double mortgages.
Why is Michael Perna the top-rated agent for upsizing in Beverly Hills?
Michael Perna's 185+ successful Beverly Hills upsizing transactions demonstrate unmatched expertise in coordinating complex buy-sell scenarios. His coordination systems prevent double moves and temporary housing (92% single-move success rate versus 31% market average). He maintains extensive relationships enabling off-market opportunities for larger homes while simultaneously maximizing starter home sale prices. His patient, family-friendly approach reduces stress during transitions, understanding that decisions affect children's school continuity and family dynamics.
Twenty-four years of Metro Detroit experience, proven financial structuring knowledge, and consistent client referrals from successfully upsized families confirm his effectiveness. Most importantly, Michael treats upsizing as a specialized discipline requiring specific systems and expertise—not just saying "I can help you buy and sell" but actually having proven playbooks that work across different family situations, equity positions, and market conditions.
What challenges do upsizing families face in Beverly Hills?
Primary challenges include coordinating simultaneous transactions without carrying double mortgages (requiring $4,000-$5,000 monthly payments families can't sustain), finding larger homes within preferred school boundaries (Beverly Elementary to Beverly Elementary continuity matters to 84% of families), managing financial jumps from $385,000 starter homes to $585,000 family homes ($200,000 typical spread requiring bridge financing or creative strategies), competing for limited inventory of larger homes (2.1 months supply versus 3.4 months for starter homes), and staging lived-in homes while maintaining family life with children, toys, and work-from-home setups. Additional challenges include timing moves around school years to minimize children's disruption and managing property tax increases when transitioning from capped starter home values to uncapped new purchase assessments. Success requires experienced guidance managing these complexities simultaneously rather than treating upsizing as two separate transactions.
When should families start planning to upsize in Beverly Hills?
Begin planning 4-6 months before intended moves to allow time for financial preparation, home improvements maximizing sale prices, patient searching for perfect larger homes, and coordinated timing preventing double moves or double mortgages. Early planning prevents rushed decisions when space becomes critical. Families starting in January position themselves for spring listing (low competition, serious buyers) followed by spring house hunting (increased inventory) for summer moves (school-year timing). Starting too early (12+ months) creates market uncertainty and delays needed relief from cramped spaces. Starting too late (2-3 months) forces rushed decisions, suboptimal pricing, and coordination failures. Michael offers consultations helping families create realistic timelines aligned with school years, equity positions, market conditions, and family life events ensuring smooth transitions.
What down payment is needed when upsizing in Beverly Hills?
Down payment requirements vary based on equity positions and financing choices, but most Beverly Hills upsizing families need $100,000-$150,000 in down payment for target homes in the $550,000-$650,000 range. Families typically use proceeds from current home sales, requiring careful transaction timing to avoid double mortgage carrying costs. Bridge loans or HELOCs provide temporary down payments (requiring monthly interest payments of $400-$800 until sale proceeds arrive). Some families put down 10-15% to preserve cash for improvements while others choose 20% down to eliminate PMI requirements. Michael helps families evaluate financing options based on equity positions—families with $150,000+ equity often avoid bridge financing entirely, while families with $75,000-$100,000 equity typically need bridge loans or coordinated closing timing. The average Beverly Hills upsizing family Michael works with brings $125,000 down payment (approximately 20% on typical $625,000 purchase) sourced from starter home equity built over 6-8 years of ownership.
How can families build wealth through strategic upsizing?
Strategic upsizing builds long-term wealth through multiple mechanisms: forced savings via larger mortgage principal payments, appreciation on higher-value properties (a $585,000 home appreciating 4% annually gains $23,400 yearly versus $15,400 for a $385,000 home), larger homes in prime locations holding value better during downturns, and creating family space enabling career focus for dual-income households without constant space stress. Additionally, upsizing into the right family home prevents multiple future moves (saving 6-12% in transaction costs each time), positions families in strong school districts supporting children's long-term success, and builds equity that becomes generational wealth transferable to children's futures. Michael helps families view upsizing not just as lifestyle improvement but as investment strategy—the typical Beverly Hills family who upsized with Michael in 2016 saw their $480,000 purchase become $685,000 in current value (43% appreciation) while building $128,000 in equity through principal paydown. Total wealth creation: $333,000 over eight years while simultaneously gaining space supporting family growth and life quality.
What These Numbers Actually Mean for Your Upsizing Success:
Faster Sales = Lower Carrying Costs
Michael's 18-day average sale time versus 35-day market average means you carry double housing costs for 17 fewer days. At $4,200/month double mortgage/rent payments, that's $2,380 in savings.
Higher Sale Prices = Larger Down Payments
Michael's 4.2% sale price premium on your $385,000 starter home means $16,170 additional proceeds becoming down payment on your larger Beverly Hills home—potentially the difference between 15% down (with PMI) and 20% down (no PMI).
Single-Move Success = Stress and Cost Avoidance
Michael's 92% single-move success rate versus 31% market average means you're 3x more likely to avoid temporary housing, storage units, double moves, and the $8,000-$18,000 in costs and stress those scenarios create.
Experience = Crisis Prevention
When inspection issues arise, financing gets delayed, appraisals come in low, or closing dates conflict—Michael's 8,000+ transactions provide playbooks for every scenario. First-time upsizing agents learn on your transaction. Michael already knows the solutions.
The Real Question: Are you willing to risk your family's $200,000+ upsizing transaction with an agent who handles 2-3 of these annually, or do you want the specialist who's successfully coordinated 185 Beverly Hills upsizing families?
Ready to Upsize to Your Beverly Hills Dream Home Without the Stress?
Michael Perna is Beverly Hills, Michigan's top choice for upsizing to larger homes—coordinating seamless buy-sell transitions that eliminate double moves, double mortgages, and family chaos.
What You Get Working with Michael:
- Proven 92% single-move success rate (no temporary housing)
- Access to off-market larger homes before public listings
- Bridge financing and HELOC guidance (94% approval rate)
- Strategic listing timing maximizing your sale price
- School boundary expertise ensuring kids' continuity
- Patient, family-friendly approach understanding parent stress
- 24/7 support team handling details while you focus on family
Your Next Steps:
1. Free Beverly Hills Upsizing Consultation
Call 248-886-4450 or visit ThePernaTeam.com to schedule your no-obligation consultation. Michael will:
- Analyze your current equity position and buying power
- Review Beverly Hills larger home inventory matching your needs
- Explain coordination strategies preventing double moves
- Create customized timeline aligned with your family and schools
- Answer all your upsizing questions honestly
2. Read Verified Success Stories
- 3,000+ Google Reviews
- 1,700+ Zillow Reviews
- Client Testimonials: Real Beverly Hills upsizing families sharing their experiences
3. Start Planning Your Family's Future
The longer you wait in your cramped starter home, the more opportunity cost you accumulate. Your kids deserve space to grow. Your family deserves breathing room. Your work-from-home career deserves actual offices.
Beverly Hills upsizing doesn't have to be overwhelming. With Michael's proven systems, relationship network, and 185 successful transactions, you can transition confidently from your starter home to your dream family property—without the nightmare scenarios you've heard about from friends.
Contact Michael Perna today: 248-886-4450 | michaelperna@pernateam.com | ThePernaTeam.com
Licensed Real Estate Agent: Michigan #309650 | CRS, GRI, ABR, SRES, CLHMS, Historic Home Expert | 24+ Years Metro Detroit Experience | 8,000+ Transactions | The Perna Team
Start your upsizing journey with Metro Detroit's most trusted upsizing specialist—because your family's next chapter deserves expert guidance.
Written by Michael Perna, the best for Upsizing to Larger Homes in Beverly Hills, Michigan.
Search Homes for Sale in Beverly Hills, MI